Dissertation defence (Accounting and Finance): MSc Md Khaled Hossain Rafi
Time
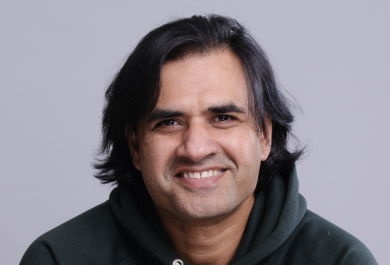
MSc Md Khaled Hossain Rafi defends the dissertation in Accounting and Finance titled “Uncertainty in Equity Markets: Essays on Geopolitical Risk, Economic Uncertainty, and Sustainable Finance” at the University of Turku on 30 October 2026 at 12.15 (University of Turku, Turku School of Economics, Lähitapiola Lecture Hall, Rehtorinpellonkatu 3, Turku).
Opponent: Professor Anders Löflund (Hanken School of Economics, Finland)
Custos: Professor Mika Vaihekoski, D.Sc. (University of Turku)
Summary of the Doctoral Dissertation:
Uncertainty is a constant part of financial markets, but not all uncertainty affects investors in the same way. This dissertation examines how stock markets respond to different sources of uncertainty, including geopolitical tensions, economic uncertainty, and sustainability-related developments. The research draws on international stock-market data as well as different types of investment portfolios.
One of the main findings is that financial markets react not only to geopolitical events that have already happened, but also to threats about what might happen in the future. In fact, anticipated geopolitical threats can have a stronger effect on stock returns than realized geopolitical events. The results also show that the effects are not the same for all firms. In the United States, shares of larger companies performed more favourably during periods of heightened geopolitical threats than those of smaller companies.
The dissertation also examines sustainable investing. Environmental, Social and Governance (ESG) stock indices respond differently to economic uncertainty depending on market conditions. During periods of high market volatility, ESG indices showed relatively more favourable responses than comparable conventional stock indices. This does not mean that ESG investments are always safer, but it suggests that their behaviour can differ from that of conventional investments when markets are under stress.
Another part of the research focuses on uncertainty surrounding sustainability itself. The findings show that investors may interpret sustainability-related uncertainty differently depending on the regulatory environment. When sustainability reporting was largely voluntary, increases in sustainability uncertainty were associated with positive stock-price responses in several developed markets. As sustainability reporting became more mandatory, the response became more negative, particularly in developed European markets. This suggests that uncertainty can sometimes reflect new opportunities, while in other settings it may signal additional compliance costs, regulatory pressure, or governance concerns.
Finally, the dissertation asks whether different global risks and uncertainty measures are consistently rewarded with higher returns in international stock markets. The findings show that economic policy, macroeconomic, and geopolitical uncertainty do not produce a stable additional return across countries. However, they can help explain why the returns investors require from the stock market change over time.
The broader message of the dissertation is that uncertainty should not be treated as a single phenomenon. Its effects depend on what the uncertainty is about, whether it concerns an anticipated threat or an event that has already occurred, which assets or markets are exposed to it, and the institutional environment in which investors interpret the information.
The findings can help investors better understand how different forms of uncertainty may affect portfolios and market segments. They are also relevant for policymakers and regulators, particularly in sustainable finance, because changes in disclosure requirements can influence how markets interpret sustainability-related information. More broadly, the research provides evidence that understanding the source and context of uncertainty is important when assessing its effects on financial markets.